French markets slide after worst protests in years
French bonds and stocks have sold off, putting fresh pressure on the euro.
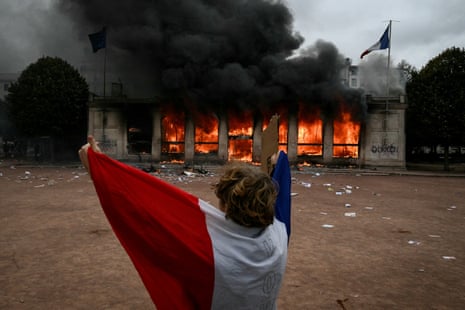
Widespread and increasingly violent protests across France have piled pressure on the government, which is struggling with weak economic growth and ballooning debt. It has yet to pass its budget for next year.
The euro fell nearly 0.4% against the dollar to $1.1201. Investors sold French government bonds, pushing yields higher.
The yield on the 10-year bond rose as much as 8 basis points to 4.86% while Germany's 10-year yield, the benchmark for the eurozone, was flat at 3.41%. The gap between them widened to 145 basis points, the highest in two years, although below the near 160bps hit in early October, when the French 10-year yield hit 4.99%, its. highest since 2002.
The ratings agency Moody's is due to review France's credit rating on Friday, which could result in a downgrade, which would pile further pressure on bonds.
French stocks slid, with the CAC 40 index down nearly 1.3%, while the broad European Stoxx 600 index lost 0.6%. Two of France's biggest lenders, Société Générale and BNP Paribas, fell by 2.5% and 2.2% respectively.
The Milan borsa fell almost 1.3% too. Investors worry that the jump in French yields could spill over into other heavily indebted parts of the eurozone. The Italian 10-year bond yield rose 5.7bps to 4.53%. Italy has also seen protests over the weekend, over fuel and food shortages.
Bastien Aillet and Hadrien Camatte, economists at French bank Natixis CIB, said:
double quotation mark The French public deficit is projected to widen to 5.4% of GDP in 2026, up from 5.1% in 2025. Although the government initially targeted a 5% deficit, several factors are expected to weigh heavily on state revenues because of lower-than-expected domestic economic activity.For 2027, the government has announced a €54bn savings plan aimed at bringing the deficit down to 5% (as opposed to an estimated 6.4% without these consolidation measures). The scale of this effort is unprecedented outside of post-crisis recovery periods. This raises significant credibility questions, particularly given that:
â–º The National Assembly remains deeply fragmented, leaving the government without a clear majority to pass these measures as originally designed;
â–º The government's 2027 GDP growth assumption of 1% appears optimistic compared to our own forecast of 0.8%.
For these reasons, we expect a deficit closer to 5.5% in 2027. Should this situation materialise in 2027, it would represent the fifth consecutive year that the government has registered a deficit exceeding 5% (the last deficit below this threshold being in 2022 at 4.7%).
Consequently, whilst France has experienced the largest increase in its debt-to-GDP ratio since the Covid-19 pandemic, it is also expected to record the sharpest rise over the next two years. Moreover, this ratio is expected to breach the 120% GDP threshold by the end of next year, representing the second-highest public debt-to-GDP ratio among the major euro area economies.
Going forward, the primary areas of concern remain the trajectory of structural spending (particularly social expenditure) and the cost of debt servicing which are expected to increase substantially in a no policy change scenario. Driven by the current high-interest rate environment, debt service charges could reach 4% of GDP by the end of the decade, compared to 2.2% in 2025.
Key events
Closing summary
France has been hit by a fresh wave of selling in its bond and stock markets after violent protests over the weekend left public buildings burned, hundreds of shops looted and thousands of arrests across the country.
Almost 2,400 people have been arrested in France, the interior ministry said on Sunday, with police deploying teargas in confrontations with protesters.
The French president, Emmanuel Macron, condemned the “unbridled violence†in a televised address on Sunday night.
“Looking at these images, we all asked ourselves: what is going through their minds? How can French people do this to France?†he said.
The chaos has spooked investors in France's government debt, with the yield on its 10-year yield rising by 10 basis points to 4.89%, and sent the euro 0.2% lower against the dollar. Bond yields rise when prices fall. The pound hit a 17-month high against the single currency.
The spread between French and German 10-year yields – which measures the premium investors pay to hold French debt over safer German bonds – has widened to 143.6bps, and is on track for its highest closing level since early 2012.
The Italian 10-year bond yield rose by nearly 10bps to 4.57%. The French stock market slid 1.5% while the Italian market lost almost 2%. The UK's FTSE 100 index was also down, 1.2%, while Wall Street stocks pushed higher, with the tech-heavy Nasdaq up 1%.
Our other main stories:
Thank you for reading. We'll be back tomorrow. Bye! – JK
Insured losses from French riots estimated at below €1bn to €1.1bn
As far as the French riots go, insured losses have been estimated at below €1bn to €1.2bn, which should be manageable for the country's insurers, according to experts.
One of the most violent days of unrest in years over the weekend left public buildings burned, hundreds of shops destroyed and looted and at least 2,400 people arrested in cities across the country.
Marcos Alvarez, global head of insurance at Morningstar, said:
double quotation mark Insured losses should remain below €1bn to €1.2bn. Assuming no further violence, we expect the latest French riots to be a manageable earnings event rather than a capital event for the country's major insurers, particularly after reinsurance recoveries and potential claims against the French State.
France has approved a new state-backed riot insurance mechanism, but it is not yet operational. The planned framework would introduce mandatory riot coverage and allow insurers to transfer a substantial share of qualifying losses to a State-backed mechanism managed by the Caisse Centrale de Réassurance (CCR), France's public reinsurer. Because the framework is still pending, the mechanism does not protect insurers against the latest riots. Riots are increasingly behaving like natural catastrophes from an insurance perspective. The key risk is having correlated claims across multiple cities at the same time. France's 2023 riots generated about EUR 730 million of insured losses, reinforcing the case for insurers and reinsurers to treat strikes, riots and civil commotion as an accumulation risk requiring dedicated pricing, limits and reinsurance.
Goldman Sachs analysts have published this note entitled Euro Area Sovereign Risk: Now vs Then.
-
European sovereign risk is back in focus as fiscal concerns have pushed French spreads to decade highs and tentative spillovers have emerged in other markets, including Italy. With this raising the question of whether the euro area could face a renewed debt crisis, we compare today's conditions with the 2011-15 episode.
-
We see several similarities. Fiscal imbalances are elevated (with further spending pressures from defence and ageing), interest rates are high and rising, and debt dynamics look concerning in several countries (including France, Belgium, Austria and Finland). Financial-market vulnerabilities also persist through sovereign exposures and non-bank leverage, while greater political fragmentation complicates the fiscal adjustment required.
-
But today's starting point is stronger in several important respects. Real and nominal growth are materially higher, household finances are more robust, external imbalances and reliance on foreign financing are smaller, and banks—especially in Southern Europe—have healthier capital, asset quality and profitability. The Euro area has also strengthened its institutional architecture through the ESM, greater common EU issuance and ECB tools to address fragmentation risk.
-
As a result, the risks of disorderly market escalation and real economy contagion look notably lower. But the fundamental fiscal challenges for some countries—especially in France—look harder now than in 2011-15. The issue of how to deal with fundamental sovereign risk remains unresolved in the Euro area, requiring credible fiscal consolidation.
Sterling hits 17-month high against euro
Sterling has hit a fresh 17-month high against the euro, as street riots â in France and elevated energy prices weighed on the single currency while recent strong economic data also helped lift the ​British currency.
The euro fell and the spread between French OAT bonds and safe-haven German Bunds widened after weeks of increasingly violent street protests in France. Natural gas prices climbed to a four-year high, although Brent crude oil price fell more than $2 a barrel to $107.83 a barrel, down 1.8%.
The pound rose 0.25% to 84.11 ​pence per euro, after hitting 83.95 ‌pence earlier in the ‌session, the strongest since May 2025.
Bank of England governor Andrew Bailey said on Friday that soaring energy prices so far appear to be having only a limited impact on UK prices, but it is too soon to draw firm conclusions about how strong second-round effects will be, for example in wage growth. Tomorrow, we will get the latest labour market data for the UK.
According â to Commerzbank, the economy's resilience could give the central bank room to ​raise rates without harming growth.
The UK economy unexpectedly continued to grow in August despite a fall in consumer spending before John Healey's first budget as chancellor.
On Wall Street, the Nasdaq has opened 276 points higher, a gain of over 1%, in contrast to the heavy losses seen in European stock markets.
The benchmark S&P 500 climbed 0.55% and the Dow Jones edged lower.
French and German 10-year bond spread on track for highest close since 2012
In the bond markets, the sell-off continues, driven by fears over governments' ballooning debt and amid a wave of street protests in France, Italy, Portugal and Albania.
France has been rocked by its worst unrest in years, as some peaceful protests turned into street riots, partly due to the police's aggressive tactics.
The yield on the French 10-year bond, obligation assimilable du trésor or OAT, has jumped 10.7 basis points to 4.88%, while the yield on the Italian equivalent is up 8.5bps to 4.56%.
As a result, the spread between French and German 10-year yields, has widened to 143.6bps, and is on track for its highest closing level since early 2012. It measures the premium investors pay to hold French debt over “ultra-safe†German bonds.
European stock markets slide
European stock markets are a sea of red.
The UK's FTSE 100 index has lost 1.3% or 140 points to 10,741, while Germany's Dax is down 1.26%, France's CAC 40 slid 1.45%, and Italy's FTSE MIB Spain's Ibex have both fallen more than 1.7%.
Here in London, losses are led by mining companies Anglo American and Glencore, along with financial stocks Barclays, NatWest Group and HSBC, and defence groups Babcock International and BAE Systems, and advertising group WPP and tobacco giant Imperial Brands.
Barclays shares dropped 3.7%, making it the second-biggest loser on the FTSE 100 index, after a report that the Bank of England is looking into Barclays' handling of loans linked to the embattled private credit sector.
The Bank's regulatory arm, the Prudential Regulation Authority (PRA), started reviewing the matter earlier this year after concerns were raised by a Barclays insider, according to the Financial Times.
The concerns related to the way Barclays logged the derivatives used to finance the loans it issues to private credit firms. Those derivatives – financial contracts that track the performance of an underlying asset – are said to have been logged in the wrong portfolio, indicating they were less risky than they actually were.
That could mean the bank was not holding enough capital to cover potential losses, and could have boosted its profitability.
Mike Ashley's Frasers Group, the owner of the Sports Direct Frasers brands, said it has slightly reduced its stake in the luxury fashion retailer Burberry, from 7.4% to 6.05%. Frasers recently bought the London department store chain Harvey Nichols out of administration and owns stakes in a number of other companies, including Germany's Hugo Boss.
Uber sees off two legal challenges in London
Gwyn Topham
Uber has seen off two legal challenges in London from black cab drivers and former private hire firms that sought to make it pay hundreds of millions of pounds in compensation.
The claims were dismissed at the High Court under the statute of limitations, with the judge ruling too much time had elapsed since the alleged offences.
The lawsuits were filed in 2024 claiming Uber had given Transport for London “misleading and inaccurate information†to obtained a private hire vehicle operating licence.
The linked claims were seeking damages of nearly £200m for around 13,000 black cab drivers, and around £140m for two ‌now-defunct companies, Kabbie and Iride.
Uber denied the allegations and argued the lawsuits were filed after the six-year limitation period. Judge Simon Birt agreed in a written ruling that the claimants could have discovered the alleged deception before 2018, six years ‌before the claims were filed, and dismissed the cases on the limitation grounds without considering the merits, Reuters reported.
An Uber spokesperson said:
double quotation mark We are pleased that the court has dismissed all of these claims entirely at the earliest opportunity and the ruling today has put these legacy matters firmly in the past.
A spokesperson for the claimants said they were “considering all options availableâ€.
Uber has massively expanded in London to the cost of black cabs and minicab firms. It was first licensed in 2012 but TfL later refused to fully renew its licence in 2017 over concerns that it was not a “fit and proper†operator.
It has now started rolling out robotaxis in London, making its own drivers fear for their jobs.
The high court ruling on Monday comes ahead of another case for Uber in London, with HMRC seeking to recover more than £1.4bn over a disputed VAT loophole.
North Sea oil workers to strike on Wednesday if Acas talks fail
A 24-hour strike by oil workers in the North Sea on Wednesday could bring down the Forties pipeline, the Unite union has warned.
The strike action will start at 06.00 hours on Wednesday 21 October and ends at 05.59 on Thursday 22 October.
The UK's largest union confirmed the strike by more than 160 Apache offshore workers is set to take place this week, having previously warned that it “severely disrupt†UK fuel supplies. It added that staff were left with no choice after a breakdown in pay talks with the Texas oil company Apache.
Talks with the conciliation service Acas are scheduled prior to Wednesday's planned strike, but the union is warning that Apache has shown no willingness to resolve the dispute.
There are seven Apache assets associated with the Forties and Beryl oil fields that will be affected. The workers involved in the dispute include electrical, instrument, mechanical and production technicians alongside telecoms technicians and radio operators.
Unite said Apache workers “emphatically backed strike action in the escalating pay dispute†after workers rejected an offer, which amounts to a real terms pay cut for many workers, ranging from a pay freeze to below inflation increases.
The operator has set deadlines for reaching an agreement over back pay, and indicated payments may be withheld which would leave workers potentially thousands of pounds out of pocket.
Unite has repeated its warning that industrial disruption could lead to the critical Charlie platform being brought to a standstill. The scenario could result in a lack of pressure that can lead to the entire Forties Pipeline System (FPS) going down.
It is estimated that more than 80 offshore fields and the St Fergus gas plant flow through pipelines into the FPS. The system operated by Ineos is reported to handle approximately 29% of the UK's oil and 30% of its gas.
The union said that a further 24-hour strike is planned, from 06.00 on 4 November until 05.59 on 5 November.
Unite general secretary Sharon Graham said:
double quotation mark Apache is part of a global company [APA Corporation] which is making billions of pounds in profit. They can easily afford to resolve this dispute without even a dent in their profits by making an acceptable offer to our members. The fact is Apache has so far chosen not to do this which is putting UK fuel supplies at risk. That is reckless behaviour and it is driven by shameful corporate greed.
Unite industrial officer Stevie Davies, added:
double quotation mark Talks are set to take place with the conciliation service Acas prior to the 24-hour strike action. We want these talks to be successful but we are not hopeful because Apache has shown no willingness to resolve this dispute.Many of our members have been offered a real terms pay cut – and that is unacceptable for an extremely profitable oil and gas operator.
We have repeatedly warned that any action could lead to a material disruption in the Forties Pipeline. This could severely affect the UK's fuel supplies. Apache not only don't seem to care for their workers, but they have shown no concern for other operators and consumers.
More than half of UK first-time buyers paying more for mortgage than they did for rent
A majority of first-time UK buyers now pay more towards their monthly mortgage bills than they used to pay in rent, the estate agent Hamptons has found.
Last month 56% of first-time buyers said their monthly mortgage bills exceeded their previous rent, the highest proportion in at least a decade, according to Hamptons. They paid £39 more on average.
Mortgage rates have been climbing in the UK since the outbreak of war in the Middle East, as volatility in the bond markets has driven up the swap rates that affect the pricing of fixed-rate deals.
Earlier this month the average cost of a five-year fixed-rate mortgage hit the 6% barrier for the first time in three years. On Monday morning the average rate stood at 5.99%, while the average rate for a two-year fixed mortgage was 5.96%, according to the financial analyst Moneyfacts.


